All Categories
Featured
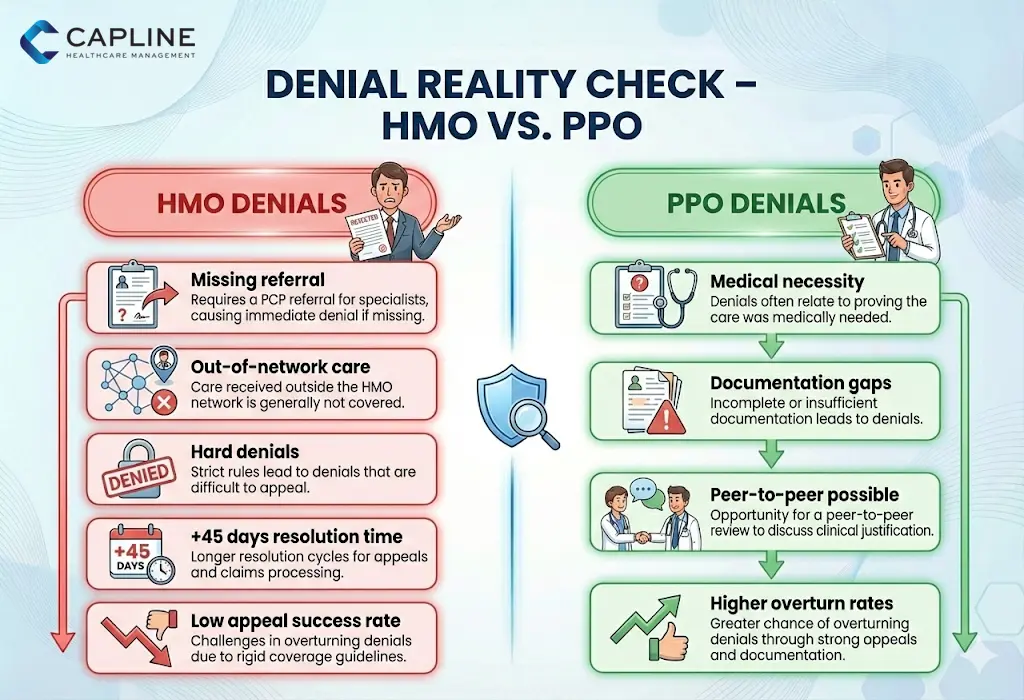
Table of Contents
An HMO Medicare Benefit strategy offers a network (referred to as an "HMO network") of healthcare suppliers and medical facilities to its customers. It's required for a patient to select a medical care physician to manage their health care and offer recommendations to any providers that are not in the plan's network, other than in the event of an emergency.
The ease of having a main care doctor to collaborate and manage the care offered. A client can only see companies within the plan's network unless they have a recommendation for an outdoors professional, or it's an emergency situation.
Nevertheless, unlike an HMO plan, a PPO Medicare Advantage strategy enables for more versatility when seeing out-of-network companies. For that reason, it's not required to have a referral to see an out-of-network specialist although it may be more pricey and take additional time to get insurance protection considering that a patient need to submit a claim for coverage each time they see an out-of-network company.
The patient has more versatility with which providers they pick to see, whether they're within the plan's network or out-of-network. Most times, there is no requirement for a referral if a patient cares to see an out-of-network expert. Higher regular monthly premium. Most most likely, greater month-to-month premiums. The client is accountable for handling their health care rather of a medical care provider.

An EPO insurance coverage plan, or an 'Special Company Organization' insurance strategy, is often called a plan that is "situated in between an HMO and PPO." This is because, like a PPO strategy, an EPO does not need a client to stay in-network for care significance, no referrals or emergencies are necessary for seeing an out-of-network company.
Current Whole Life Insurance Rates for American Families
This strategy is less widely understood, it often offers a much bigger network than an HMO.A POS insurance coverage plan, or a 'Point of Service' insurance plan, is likewise understood to "blend elements of HMO and PPO strategies." This is because, like an HMO strategy, a POS insurance coverage strategy requires a client to have a medical care medical professional that manages their health care and provides recommendations to out-of-network specialists or companies.
, the deductible is at least $1,400 for an individual and $2,800 for a household. In order to combat the high deductible cost, it is suggested that a client contributes to an HSA/HRA or a 'Health Cost Savings Account'/'Health Compensation Plan,' which employers frequently contribute to yearly.
Another element to note about this strategy is that it safeguards the patient from "catastrophic out-of-pocket expenses for covered services." What this indicates is that, once a patient's "annual out-of-pocket expenditures for covered services from in-network suppliers, including deductibles, copayments, and coinsurance, reaches the fixed catastrophic limitation," the insurer will cover all expenses.
HMO and PPO plans share particular functions. Both use a broad network of service providers to choose from, both offer emergency situation care coverage throughout the United States, and both usually consist of coverage for prescription drugs. There are some primary differences between HMO and PPO plans. HMO plans need members to select an in-network PCP to help manage their care and offer referrals.
How Whole Insurance Builds Family Wealth
HMOs will not cover care from an out-of-network company. PPOs will, but you'll likely save when you remain in network. HMOs generally have lower premiums and out-of-pocket costs. PPOs may cost more, but they use more flexibility.
Insurance in Long Beach CAIt's good to have options. When it comes to health insurance coverage, you have your option of several plan types. Two popular types you'll often see are HMO and PPO. Differences between HMO (Health Maintenance Company) and PPO (Preferred Company Organization) strategies include network size, capability to see professionals, expenses, and out-of-network coverage.

An HMO gives you access to specific physicians and hospitals within its network. A network is comprised of service providers that have accepted lower their rates for plan members and likewise fulfill quality standards. Unlike PPO strategies, care under an HMO plan is covered just if you see a supplier within that HMO's network.

Latest Posts

Essential Tips on 2026 Medicare Part D Enrollment
Term Life Insurance Cost Factors for 2026

Evaluating Indexed Universal Life Policies for Retirement